for institutional deal workflows
Every time A-REITs trade below asset backing, the same screen gets run: rank the sector by discount to NTA, and call the deepest discounts takeover targets. It is intuitive, it is everywhere, and the history of Australian listed property privatisations says it is not always right.
In June 2026 a Brookfield and GIC consortium completed the roughly A$4 billion privatisation of National Storage REIT at $2.86 per security, a 26.5% premium to the undisturbed price (Green Street News; TipRanks, December 2025). That deal landed while the median A-REIT still traded at an 11.9% discount to NTA (BDO, A-REIT Survey 2025), and while the deepest-discount names in the sector attracted no completed bid at all.
So this piece does the math's at first principles: nine take-private situations across a decade, what price each bid actually landed at relative to NTA, what the register looked like when it did, and who was writing the cheques. Three patterns fall out, and none of them is "buy the biggest discount".
The Market Snapshot: What the Record Actually Shows
The dataset is nine whole-register contests for ASX-listed REITs between 2016 and 2026, each one either completed or formally withdrawn at the endgame, chosen because together they span the full range of sectors, registers and outcomes.
Note: It is not an exhaustive census: contested stake builds that never became offers, scrip mergers between listed vehicles, vehicles holding purely offshore assets, and indicative approaches that evaporated before binding terms all sit outside it, and the instructive special case of the failed office bids gets its own treatment below. Aveo, Astro Japan, Westfield trades ect. excluded on basis set above.
The nine to investigate:
- Growthpoint's $321 million offer for GPT Metro Office Fund in 2016 (Growthpoint);
- ESR's $723 million takeover of Propertylink in 2018, launched off a 19.9% pre-bid stake (Corrs Chambers Westgarth, December 2018);
- Oxford Properties' $3.4 billion purchase of Investa Office Fund in 2018 after an auction against Blackstone (Reuters, September 2018);
- Macquarie's agricultural fund winning VitalHarvest in 2021 after a bidding war with Roc Partners forced it to raise its offer ten times, from $1.00 per unit to a matched $1.33, a 33% escalation (Fruitnet, June 2021; Commercial Real Estate, April 2021);
- Charter Hall and Hostplus taking ALE Property Group for an implied $5.88 per security in 2021 (Charter Hall, September 2021);
- Charter Hall and PGGM's A$1.3 billion acquisition of Irongate in 2022 (IPE Real Assets, January 2022);
- Charter Hall Retail REIT and Hostplus taking Hotel Property Investments in 2024-25 via an on-market creep;
- Ki Corporation and Public Storage's withdrawn 2025 tilt at Abacus Storage King; and
- Brookfield-GIC's National Storage deal, implemented in the second quarter of 2026 (Green Street News, 2026).
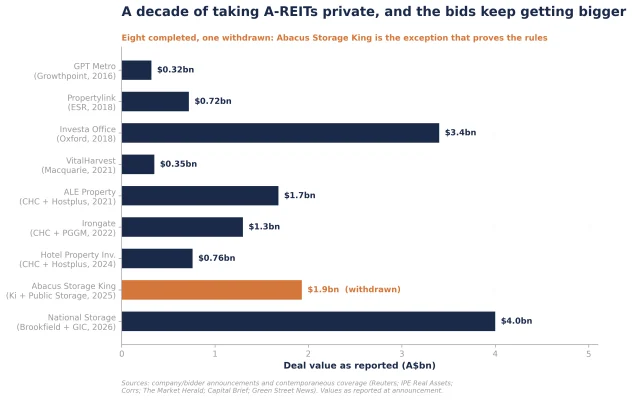
Eight of the nine completed. The values are getting larger, the later deals cluster in long-WALE and operating-platform sectors (pubs, storage), and the deepest-discount corner of the market, office, appears exactly once, at the top of the last cycle in 2018. Hold that thought.
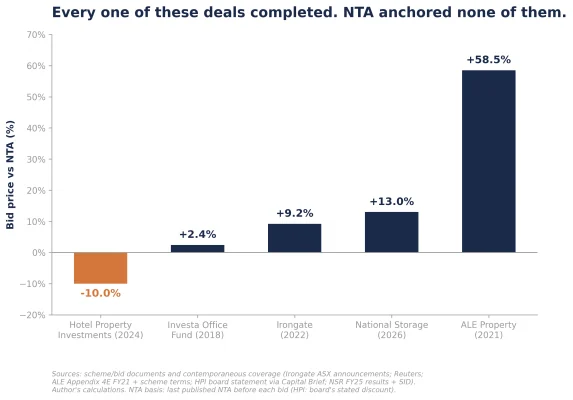
The second thing the record shows is the range of outcomes against NTA, and it is far wider than most investors assume. Oxford's final $5.60 for Investa Office (IOF ASX announcement, November 2018) was a 2.4% premium to its $5.47 NTA (Reuters, September 2018). Irongate went at a 9.2% premium to NTA (Irongate ASX announcement, January 2022). National Storage went at roughly 13% above its June 2025 NTA of $2.53 (NSR FY25 results; scheme terms). ALE went at an implied $5.88 against a June 2021 NTA of $3.71, a 58% premium to stated asset backing (ALE Appendix 4E FY21; Charter Hall, September 2021). And Hotel Property Investments was taken out at $3.85, a price its own board rejected as being about 10% below NTA (Capital Brief, 2024). Same country, same decade, same deal type: bids from 10% under to 58% over asset backing, and every one of them completed.
View 1: The Register Is a Trigger, Not the Discount
If the discount does not predict bids, what does? Look at where each situation was actually decided...on the register.
ESR did not bid for Propertylink and then buy shares; it built a 19.89% stake through market raids in 2017 and bid off the platform a year later (Corrs Chambers Westgarth, December 2018). VitalHarvest's auction ran for months and lifted the price 33%, but the contest was always going to be settled by MIRA's 20.9% blocking stake, which meant Roc could never assemble the unitholder support to win regardless of price (Fruitnet, June 2021). Hotel Property Investments is the purest case in the dataset: the board rejected $3.85 as roughly 10% below NTA, and it did not matter, because Charter Hall and Hostplus went from under 20% of the register in September 2024 to 52.38% by mid-December, the offer went unconditional over the board's continued opposition, and compulsory acquisition followed within months once acceptances passed 90% (Capital Brief, December 2024; Commercial Real Estate, December 2024). The NTA argument was correct but the register argument won.
Now run the logic in reverse. Ki Corporation already owned 59.4% of Abacus Storage King when it bid $1.47 with Public Storage in April 2025 (IPE Real Assets, April 2025). No creep was available to pressure anyone; the only path was a negotiated scheme, which handed the independent board genuine veto power. The board held its value line through a raised $1.65 offer, and the consortium withdrew in August 2025, stating it was unable to match the independent board committee's value assessment (Public Storage, August 2025). And National Storage sits at the other pole: no disclosed pre-bid stake at all, a clean register, and consequently a clean price, a 26.5% premium to undisturbed (TipRanks, December 2025).
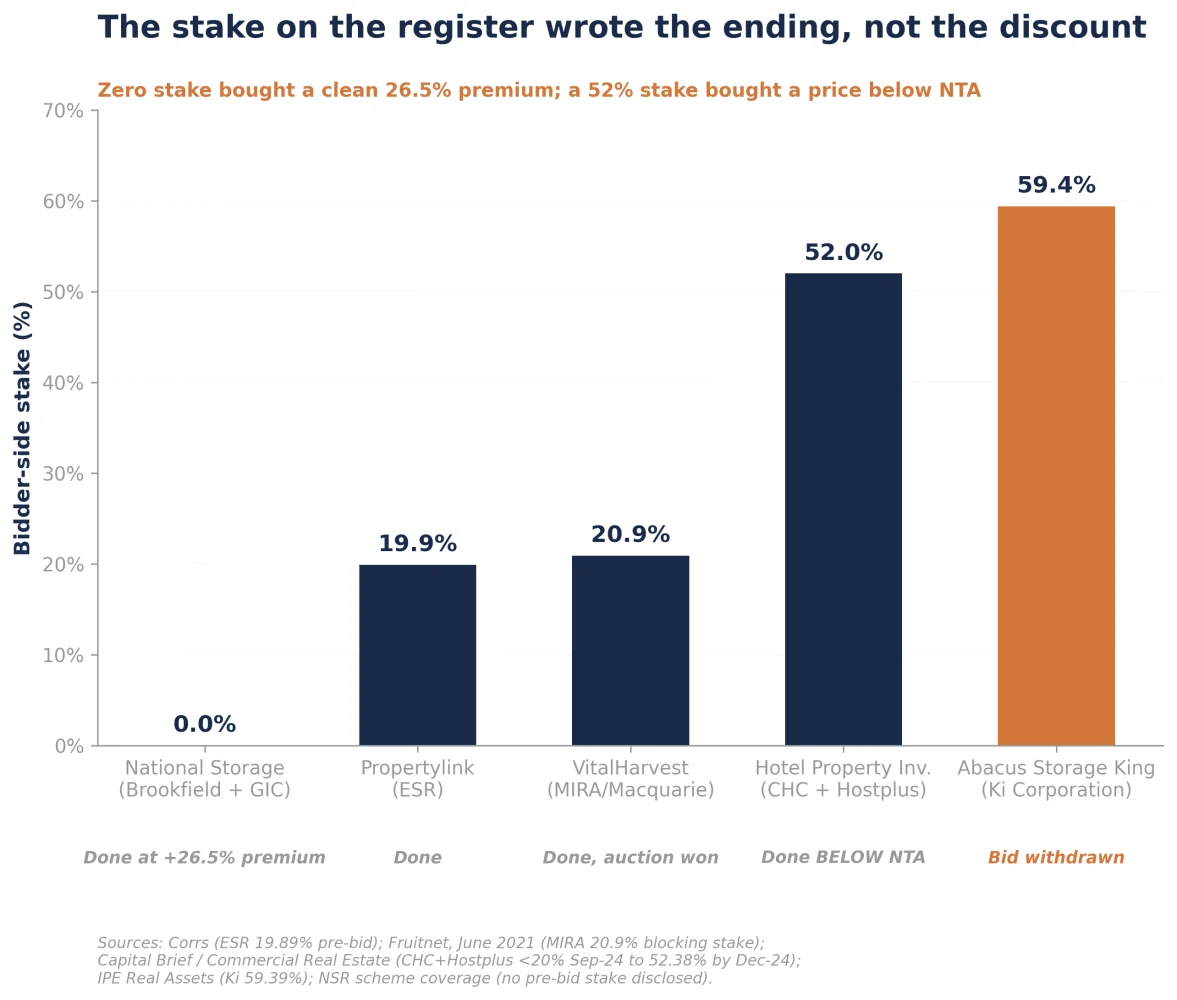
The pattern is close to mechanical. A stake near 20% starts deals and settles auctions. A creep past 50% ends the price negotiation entirely, NTA or no NTA. A dominant insider stake paradoxically protects minorities, because it forces the scheme route and gives the independent directors real leverage. And a clean register is the most expensive register: with no foothold, the bidder pays the full control premium. If you want to predict the next take-private, the substructure of the register tells you more than the size of the discount ever will.
View 2: NTA Is a Negotiating Position, Not a Valuation
Figure 2 should also change how you read the NTA number itself. If bids can complete from 10% below to 58% above asset backing, then NTA is not functioning as a valuation in these contests. It is functioning as a negotiating position, and each side treats it exactly that way.
The reason is one this newsletter covered in the last edition: an NTA is a stack of individual asset valuations, each one a capitalisation of income at a valuer's chosen yield, struck without a bid at the door. A take-private is the private market running its own underwrite of the same portfolio, asset by asset, with its own view of rents, incentives, capex and exit yields. Sometimes that underwrite lands near the valuer's (Investa Office at +2.4%, Irongate at +9.2%). Sometimes it lands miles above, and the gap is information: ALE's pubs carried leases that were materially under-rented against market, and the buyers priced the reversion the valuations had not yet recognised; ALE's own accounts had NTA rising 24% in the final year as those valuations caught up (ALE Appendix 4E FY21). And sometimes the private underwrite lands below the book, as at HPI, where the bidders simply disagreed with the valuers and had a register position strong enough to make their number the clearing price.
The practical read for investors: when a bid arrives, the debate that matters is never "price versus NTA". It is "whose underwrite of the portfolio is right", and the NTA is just one side's opening exhibit. Boards that understood this (Abacus Storage King's independent committee, which fought on value rather than on the book number, letting due diligence test the bidder's underwrite) kept control of the outcome.
View 3: The Buyers Are Retirement Capital Now
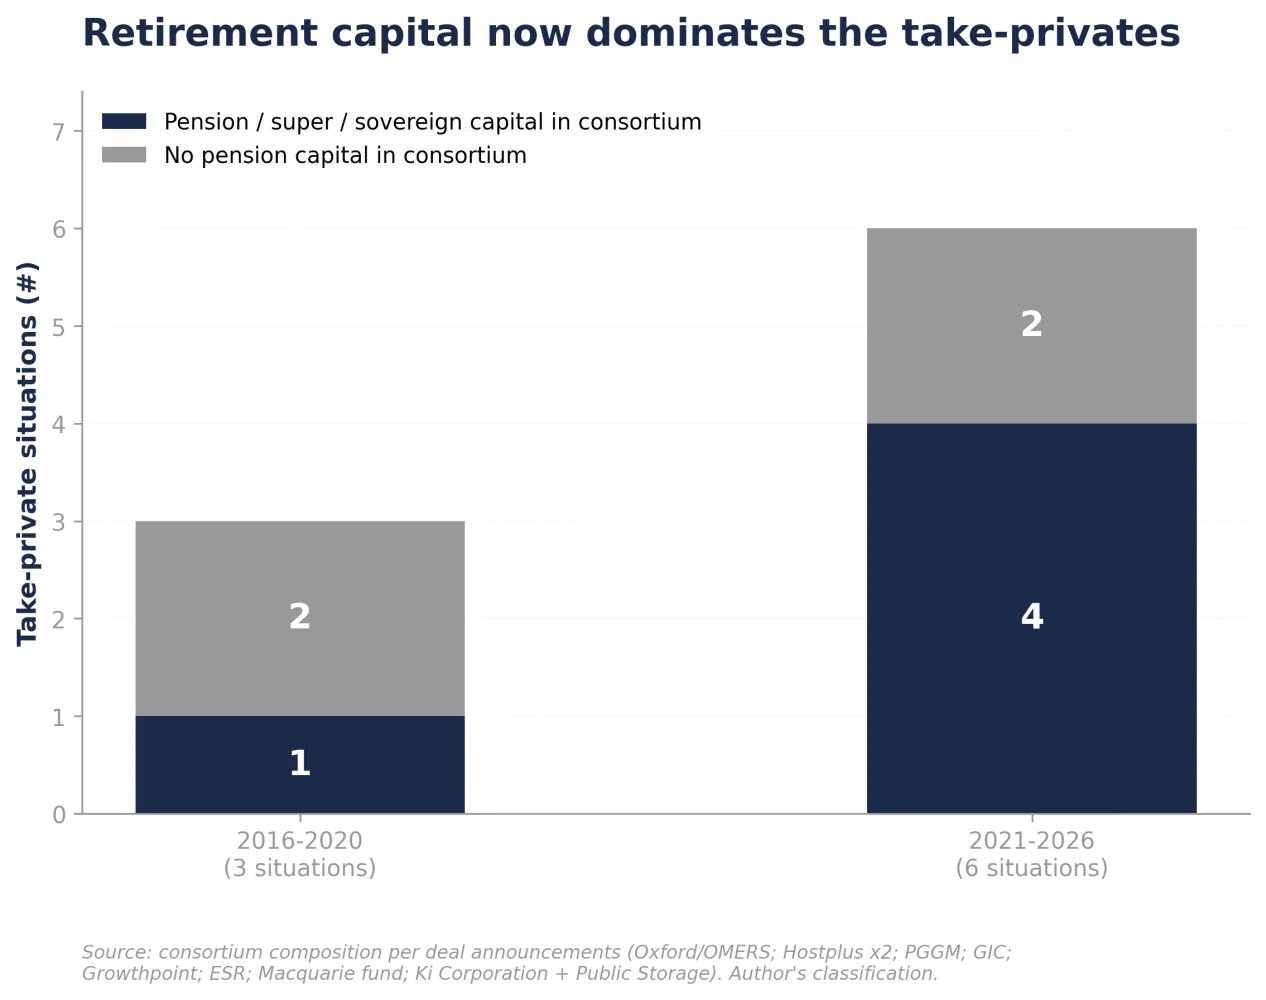
The third pattern is about who is on the other side of these deals, because it has quietly consolidated. The smaller early situations were trade and manager-led: Growthpoint, ESR, a Macquarie fund. But pension capital arrived with the biggest deal of the first era, since Oxford Properties is the real estate arm of Canadian pension plan OMERS, and it has dominated everything since: Hostplus funded half of ALE in 2021 and half of HPI in 2024 (Charter Hall, September 2021; Capital Brief, December 2024); Dutch pension manager PGGM held 88% of the Irongate partnership (Charter Hall, March 2022); and GIC stands alongside Brookfield in National Storage. Four of the six situations since 2021 had pension or sovereign capital in the consortium, against one of three in the era before (author's classification from deal announcements).
This matters for prediction because retirement capital does not buy discounts; it buys sectors and platforms. Hostplus did not underwrite ALE and HPI because pubs screened cheap; it wanted very long WALE income streams matched to very long liabilities, and it paid through NTA to get one of them. GIC and Brookfield wanted the largest storage platform in the country, an operating business with pricing power, and paid a 26.5% premium for control of it (TipRanks, December 2025). Public Storage and Ki wanted the second storage platform and still would not stretch past their underwrite.
The buyer set explains the sector pattern in Figure 1 better than any discount table: long-WALE income and operating platforms keep getting bid because that is what this capital is mandated to own. Traditional rent-collecting office towers in a structurally repricing leasing market are not, which is why the deepest discounts in the sector keep going unbought. The nearest thing to an exception proves the point: Australian Unity Office Fund, a deep-discount office vehicle, drew four separate approaches between 2018 and 2021, from Starwood Capital at $2.87 and again at $2.98, then from a Charter Hall and Abacus consortium at $2.95 and $3.04, and not one of them completed; the fund ultimately chose asset sales, capital returns and wind-up over waiting for a fifth (Mingtiandi, 2021; IPE Real Assets, 2019 and 2021; The Urban Developer). Office bids get attempted. In the current buyer set's hands, they do not close.
Where This Goes From Here
Put the three patterns together and you get a screen that looks nothing like the one the market runs. Today the sector median discount is 11.9% (BDO, A-REIT Survey 2025), and the widest discount in the sector belongs to office: Centuria Office REIT trades at $0.86 against a June 2026 NTA of $1.66, a discount of roughly 48%, and this is despite a year of solid execution: portfolio occupancy held around 91% on near-record leasing of some 40,000 sqm across 47 transactions in FY26 (Centuria Office REIT FY26 results; Stock Analysis, 17 September 2026). The market is pricing the sector, not the management.. The discount screen says that is the most obvious target in the market. The take-private record says almost the opposite: the median completed bid in our dataset landed at a 9.2% premium to NTA, in sectors retirement capital wanted, on registers that offered a path to control. The bids have been landing near the middle of the discount table, not the bottom of it.
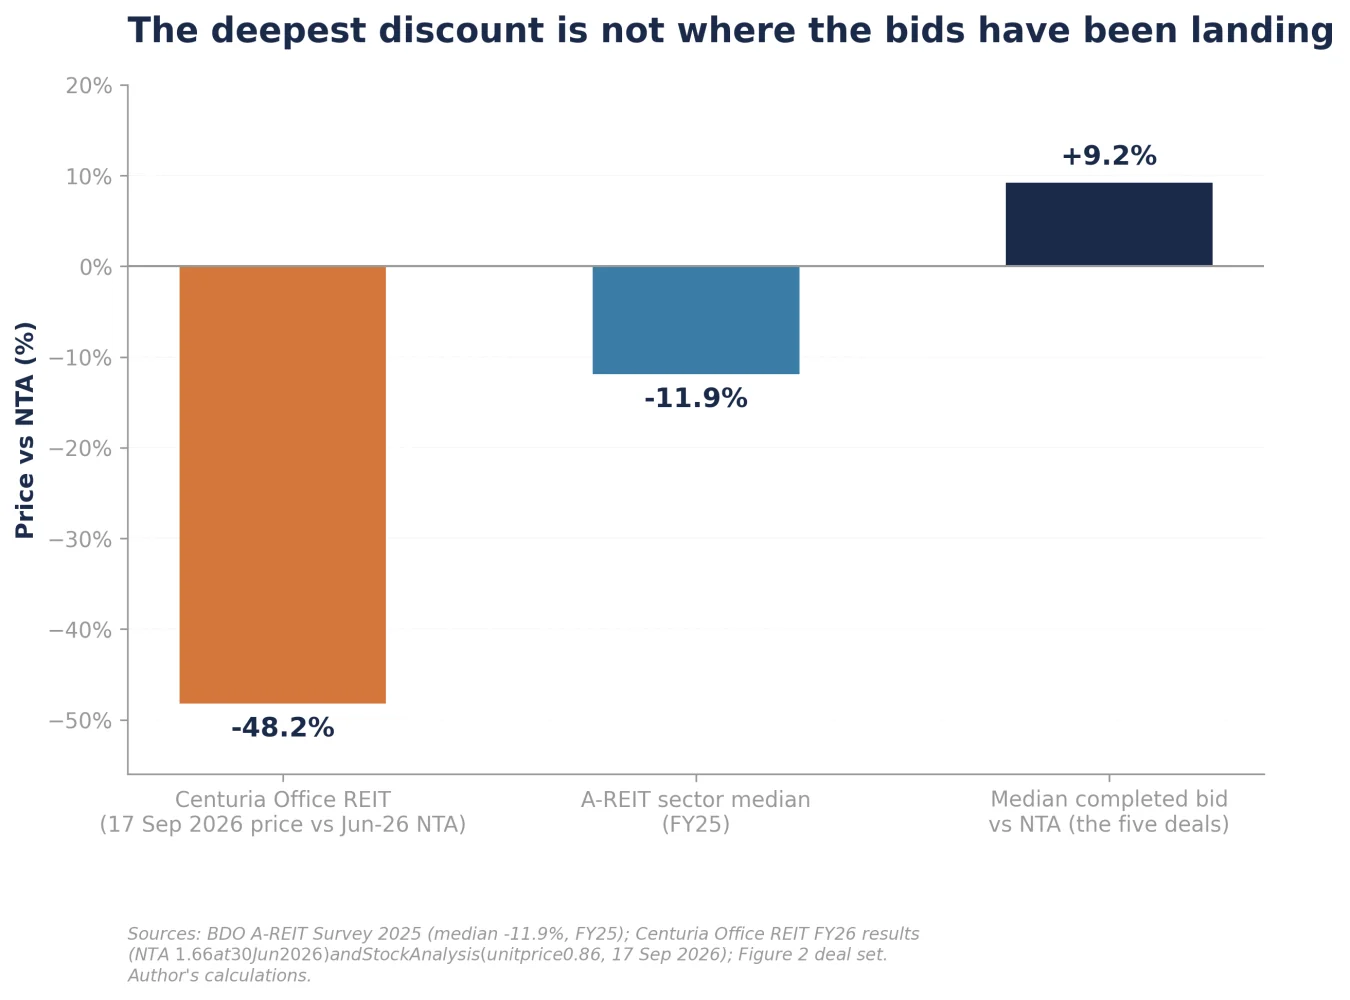
None of this is a prediction about any individual name, and it is worth being explicit that a 48% discount is not a mispricing you can arbitrage by hoping for a bidder; it is the listed market's live underwrite of office income risk, and as the last edition argued, the debate between that underwrite and the valuers' is settled deal by deal, not by assertion.
What the record does support is a checklist. A take-private needs four things at once:
- A sector the new buyer set is mandated to own;
- an underwrite, not an NTA, that clears the bidder's cost of capital, which is harder work in 2026 with the cash rate at 4.35% and the 10-year bond near 4.7% (RBA; Colliers, Quarterly Asset Class Snapshots Q2 2026);
- a register with a path, whether that is a foothold to build from or a clean register a full premium can clear;
- and a board that knows which of those two games it is in.
My view: selectively bullish on more A-REITs leaving the screen over the next two to three years. National Storage was not the end of a cycle; it was proof that the largest pools of capital in the world will pay control premiums for the right Australian platforms while the discount hunters wait at the bottom of the table for bids that history says rarely come. The NTA discount tells you a stock is unloved. The register, the sector and the buyer's mandate tell you whether it is wanted.
Sources
- Reuters (via Business Standard), Canada's Oxford battles Blackstone for Australia property with $2.4 billion Investa offer (IOF NTA $5.47), September 2018, https://www.business-standard.com/article/reuters/australia-s-investa-office-fund-gets-2-4-billion-takeover-offer-from-oxford-properties-118090400296_1.html
- Investa Office Fund, ASX announcement (Oxford proposal at $5.60 cash per unit), 6 November 2018, https://announcements.asx.com.au/asxpdf/20181106/pdf/4401fl2mr885m0.pdf
- Oxford Properties, Oxford Properties acquires Investa Office Fund for A$3.4 billion, 14 December 2018, https://www.newswire.ca/news-releases/oxford-properties-acquires-investa-office-fund-for-a34-billion-c33-billion-702763382.html
- Corrs Chambers Westgarth, Corrs advises ESR on A$723 million takeover bid for Propertylink, December 2018, https://www.corrs.com.au/news/2018/12/corrs-advises-esr-on-a-723-million-takeover-bid-for-propertylink
- Growthpoint Properties Australia, History (GPT Metro Office Fund offer, 2016), https://growthpoint.com.au/history
- Fruitnet, Vitalharvest takeover completed (MIRA's 20.9% blocking vote; offer price up 33% over the bidding war; MIRA's tenth raise matching Roc's $1.33), 15 June 2021, https://www.fruitnet.com/asiafruit/vitalharvest-takeover-completed/185510.article
- Commercial Real Estate, Roc Partners trumps Macquarie with 'binding' Vitalharvest offer (MIRA's opening $1.00 per unit offer, November 2020; matching rights), April 2021, https://www.commercialrealestate.com.au/news/roc-partners-trumps-macquarie-with-binding-vitalharvest-offer-1041287/
- Charter Hall, Charter Hall Long WALE REIT: Acquisition of 50% of ALE Property Group, September 2021, https://www.charterhall.com.au/News/news-article/2021/09/19/charter-hall-long-wale-reit-acquisition-of-50-of-ale-property-group
- ALE Property Group, ASX Appendix 4E, Full Year Report FY21 (NTA $3.71 at 30 June 2021), August 2021, https://www.aspecthuntley.com.au/asxdata/20210804/pdf/02403562.pdf
- IPE Real Assets, Charter Hall, PGGM make A$1.3bn bid for ASX-listed REIT Irongate, January 2022, https://realassets.ipe.com/news/charter-hall-pggm-make-a13bn-bid-for-asx-listed-reit-irongate/10057737.article
- Irongate Group, ASX announcements January-May 2022 (offer at $1.90, 9.2% premium to NTA), https://irongategroup.com.au/sites/default/files/announcements/2022-05/ASX%20Announcement%20-%20Scheme%20Booklet_0.pdf
- Capital Brief, coverage of the Hotel Property Investments takeover, 2024-2025 (board rejection at ~10% below NTA; stake build to 52% by 18 December 2024; compulsory acquisition), https://www.capitalbrief.com/briefing/hpi-shares-lift-as-it-tells-shareholders-to-accept-charter-hall-hostplus-buyout-27f2f3be-72fc-4a9a-ae43-f876505ad180/
- Commercial Real Estate, Charter Hall clears first hurdle in fight to control big name pubs ($760m offer unconditional at 52.38% acceptances), December 2024, https://www.commercialrealestate.com.au/news/charter-hall-clears-first-hurdle-in-fight-to-control-big-name-pubs-1342279/
- IPE Real Assets, Public Storage and Ki launch A$2bn bid for Abacus Storage King, April 2025, https://realassets.ipe.com/news/public-storage-and-ki-launch-a2bn-bid-for-abacus-storage-king/10129891.article
- Public Storage, Ki Corporation and Public Storage Withdraw Offer to Acquire Abacus Storage King, August 2025, https://investors.publicstorage.com/news-events/press-releases/news-details/2025/Ki-Corporation-and-Public-Storage-Withdraw-Offer-to-Acquire-Abacus-Storage-King/default.aspx
- TipRanks / The Globe and Mail, National Storage REIT Agrees to $4 Billion Acquisition by Brookfield and GIC Consortium (scheme at $2.86, 26.5% premium to undisturbed), December 2025, https://www.theglobeandmail.com/investing/markets/markets-news/Tipranks/36516976/national-storage-reit-agrees-to-4-billion-acquisition-by-brookfield-and-gic-consortium/
- Green Street News, Shareholders give green light to Brookfield and GIC's $4bn takeover of National Storage REIT, 2026, https://greenstreetnews.com/article/shareholders-give-green-light-to-brookfield-and-gics-4bn-takeover-of-national-storage-reit/
- National Storage REIT, FY25 results (NTA $2.53 at 30 June 2025), via MarketScreener, https://www.marketscreener.com/news/national-storage-reit-reports-earnings-results-for-the-full-year-ended-june-30-2025-ce7c51d3da8df520
- BDO, A-REIT Survey 2025 (median discount to NTA of 11.9% in FY25), https://www.bdo.com.au/en-au/insights/real-estate-construction/a-reit-survey-2025
- Centuria Office REIT, FY26 results (NTA $1.66 at 30 June 2026), https://www.investing.com/news/company-news/centuria-office-fy26-slides-leasing-strength-distribution-cut-to-9-cpu-93CH-4832707; unit price $0.86 via Stock Analysis, 17 September 2026, https://stockanalysis.com/quote/asx/COF/
- Mingtiandi, Starwood Recommits to Bid for Australian Unity REIT ($2.98 offer, 2021; prior $2.87 approach), https://www.mingtiandi.com/real-estate/finance/starwood-recommits-to-bid-for-australian-unity-reit/
- IPE Real Assets, Charter Hall and Abacus bid for Australian Unity Office Fund; The Urban Developer, AOF bid coverage ($2.95 and $3.04 proposals; wind-up and asset sales), https://realassets.ipe.com/news/charter-hall-and-abacus-bid-for-australian-unity-office-fund/realassets.ipe.com/news/charter-hall-and-abacus-bid-for-australian-unity-office-fund/10031516.fullarticle
- Colliers, Quarterly Asset Class Snapshots Q2 2026 (10-year government bond near 4.7%), https://www.colliers.com.au/en-au/research/quarterly-asset-class-snapshots-q2-2026
- Author's calculations across the deal set (premiums/discounts to NTA; buyer classification). Full workings in generate_charts.py in this folder.